Your Local Mortgage
Lender
Located in Friendswood, Texas
Personalized Mortgage Solutions. Local Expertise. Exceptional Service.
Choosing a mortgage is about more than finding a competitive interest rate—it's about finding the financing strategy that's right for your goals. As an independent mortgage advisor with Mylo Mortgage, I have access to a wide range of loan products through multiple lenders. That allows me to compare options and recommend the solution that best fits your financial situation.
Whether you're a first-time homebuyer, purchasing your next home, investing in real estate, or refinancing, you'll receive personalized guidance, proactive communication, and a mortgage process designed to be as smooth and stress-free as possible.
From your initial pre-approval through closing—and long after you've settled into your home—I'm committed to being a trusted resource you can rely on.
Ready to take the next step? I'd love the opportunity to help you achieve your homeownership goals.
The Home Loan Process
Mortgage Pre-Approval
Get pre-approved from one of our Loan Officers to see how much you can afford.
House Shopping
Work with a trusted Real Estate Agent to find a home you would like to move into.
Loan Application
Complete your home loan application to get the lending process started.
Don't take my word for it
Mortgage Programs
Experience the best mortgage experience located in Friendswood, Texas.
Home Loan Options
Our experienced mortgage advisors will walk you through the best mortgage loan program that will fit your specific scenario.
Conventional Home Loans.
FHA Home Loans.
Jumbo Loans
VA Home Loans.
Frequently Asked Questions
How often can I refinance my mortgage?
There is no limit to the number of times you can refinance. However, you must qualify every time you apply and there will be costs associated with closing the loan each time.
Can I buy a home if I do not have money for a down payment?
Yes! There are a number of bond programs that offer low or no down payment financing options.
How do I know which mortgage is right for me?
The key to choosing the right mortgage is to understand the range of options and features available to you, as well as your budget, circumstances, and goals. Our licensed mortgage professionals are here to help you navigate that process. The more you know, the more comfortable and confident you will be choosing the best option for you and your family.
How long will the loan process take?
The Truth in Lending Act (TILA) does not permit a lender to close a loan until at least seven (7) business days have passed from the date your application was received. A typical home loan takes 30 days, as a number of third-party services such as appraisals, title work, and credit are required in conjunction with the mortgage process. Once you familiarize your Loan Officer with the details of your specific loan scenario, they will be able to provide you with a more specific timeline.
Will I qualify for a home loan?
The only way to find out is to speak with a qualified mortgage professional. Our Loan Officers have helped numerous clients who didn’t know if they could qualify to become home owners. We take the time to understand your financial situation and long-term financial goals, and then match you with the loan program that best fits your needs. Your approval for a loan may also largely depend on the price of the home you are financing. Getting pre-qualified prior to beginning your home search can give you an idea of what you may be able to afford.
Why do people refinance their mortgages?
Homeowners typically refinance to save money, either by obtaining a lower interest rate or by reducing the term of their loan. Refinancing is also a way to convert an adjustable loan to a fixed loan or to consolidate debts.
How much money will I have to pay upfront to buy a home?
This question does not have a simple, one-size-fits-all answer. The exact amount will depend on the price of the home you buy as well the type of mortgage financing you choose. Depending on your loan program, your down payment could be as much as 20% of the home’s price or as little as 3%, while some loans require no down payment at all.
Can I get a mortgage after bankruptcy?
You may still qualify for a home loan even if you have experienced a bankruptcy. The best way to find out if you qualify is to talk with a Loan Officer to discuss your options. Be sure to bring all paperwork regarding your bankruptcy so your Loan Officer can find the program that best fits your situation.
Should I lock my interest rate now, or wait until we are closer to our closing?
Interest rates fluctuate all day, every day. If an interest rate is good, it may be in your best interest to lock now. If you wait, you run the risk of an increase in rates later. If you are concerned that rates may go down after you lock, contact your Loan Officer to discuss your options. Some programs allow you to lock for an extended period and choose to lower your rate should a better one become available.
Most Recent Blog Updates
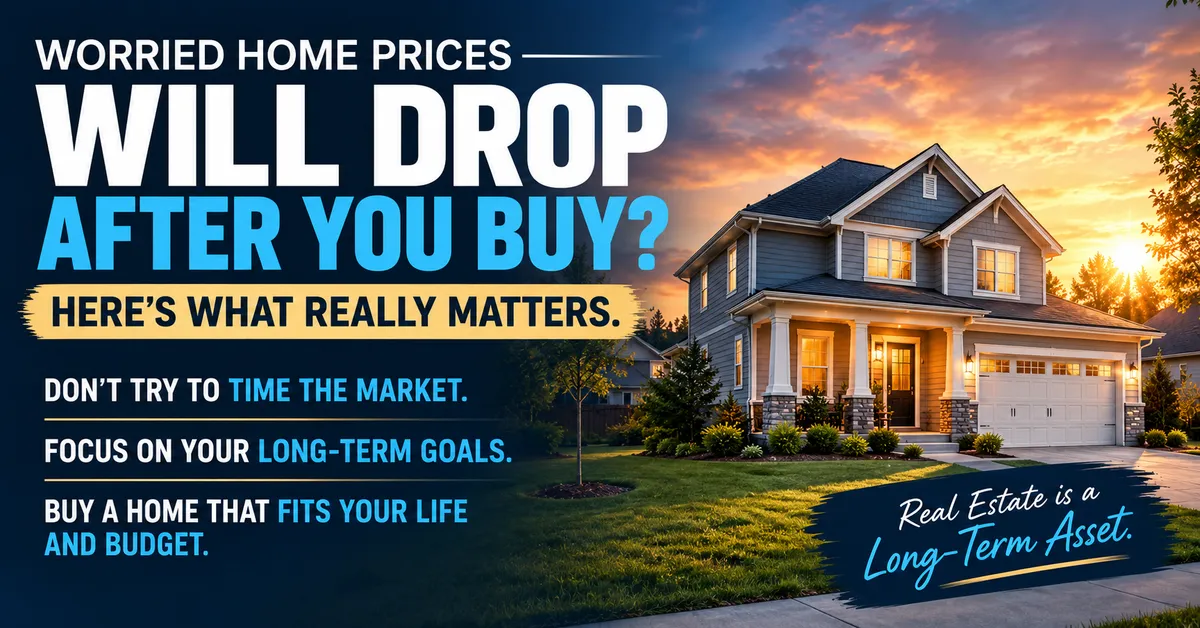
What If Home Prices Drop After I Buy and Here Is the Honest Answer Every Buyer Deserves to Hear
The Fear That Is Keeping More Buyers on the Sidelines Than Almost Anything Else
What happens if I buy a home and prices drop after I purchase? Michele Green hears this question consistently from buyers right now and she takes it seriously rather than dismissing it. It is a fair concern that deserves a direct and honest answer rather than reassurance designed to move someone toward a transaction they are not ready for.
Why Timing the Market Is Not the Strategy It Appears to Be
The fear behind this question rests on an assumption that buying at the right moment is both possible and predictable. It is neither. Even experienced real estate investors and professional analysts with full-time research teams cannot consistently identify the exact top or bottom of a market cycle. A buyer who is also managing a career, a family, and every other demand of daily life is not going to out-predict the professionals who do this exclusively.
That is not a discouraging observation. It is actually a liberating one. If timing the market perfectly is not a realistic goal then the energy spent trying to achieve it is better directed toward questions that actually have useful answers.
The Question That Actually Matters
Does the home make sense for your long-term goals? That is the question worth spending time on.
A home purchased with a payment that fits the budget, in a location that genuinely serves the family's needs, and held through the natural appreciation cycle that real estate has historically produced over time is a sound financial decision regardless of what happens to prices in the near term. Homeowners who focus on building equity over time have been consistently rewarded by the long-term nature of real estate as an asset class.
The buyer who purchased before a temporary price decline and held through it came out significantly ahead over a longer horizon. The buyer who waited for the perfect entry point and missed years of recovery appreciation did not necessarily fare better despite avoiding the short-term discomfort.
What to Focus on Instead
Rather than asking whether prices might drop next month or next year the productive framework is grounded in what is knowable right now. Is this the right home for your family's actual situation? Does the payment work comfortably within your real budget? Does buying make sense given your income stability and your plans for the next five to seven years?
If the answers to those questions are yes the short-term price movement in either direction is a minor variable in a much longer equation. Real estate rewards patience and appropriate holding periods far more reliably than it rewards market timing.
Reach out to Michele Green to run the numbers on your specific situation and find out whether buying the right home at a payment that works for your budget makes sense for your long-term goals right now.
Sources
NAR.realtor
MortgageNewsDaily.com
FederalReserve.gov
ConsumerFinancialProtectionBureau.gov
Investopedia.com

Mortgage Calculator
See your total mortgage payments using the tool below.
| Year | Interest | Principal | Balance |
|---|

